NPV, IRR and payback: is the investment worth it?
Compare discounted value, periodic return and cash recovery using consistent forecasts and tested investment examples.
By Dr. Hassan Khames EliwaLast updated
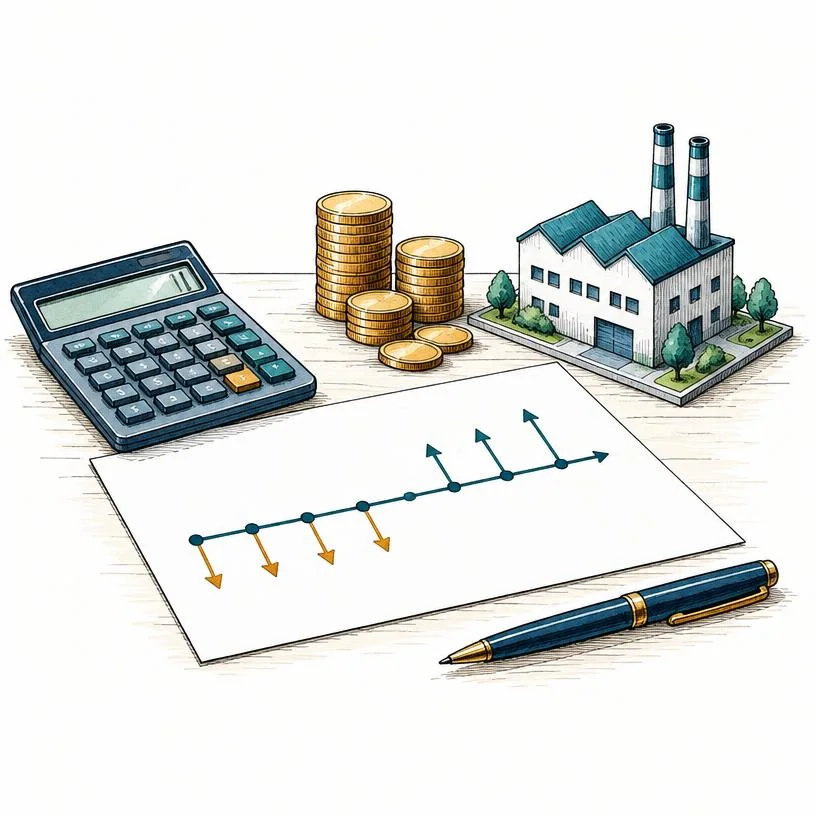
Three outputs, three different questions
Net present value measures discounted inflows less discounted outflows at a chosen required return. Internal rate of return is a discount rate that makes those cash flows’ NPV zero. Payback measures how long receipts take to recover the initial investment, ordinarily without discounting unless the measure says otherwise.
NPV asks about value, IRR expresses a rate and payback highlights recovery speed. A proposal can pay back quickly while adding little discounted value. Another can show an impressive percentage yet add fewer dollars than a larger alternative. Do not vote among the outputs. Decide what the business needs to know and interpret each in that role.
Use the NPV calculator, IRR calculator and payback period calculator with the same forecast. The calculators take an initial cost as a positive amount and subtract it internally. In the written cash-flow vector, that same time-zero cost is negative. Changing the forecast between methods defeats the comparison.
Put cash on a timeline before using a formula
Identify incremental cash receipts and payments from doing the project rather than not doing it. Include relevant operating costs, working capital, tax effects and eventual disposal. Accounting profit is not a substitute. Depreciation is not itself a cash payment, although its tax consequences can change cash flows.
Here, receipts are net incremental amounts at annual period ends. Taxes, inflation, working capital and residual value are excluded to make the arithmetic reproducible. Those are teaching assumptions, not a recommended checklist for a real investment. OpenStax’s Principles of Finance explains the wider capital-budgeting methods and their limitations.
| Measure | Meaning | Main limitation |
|---|---|---|
| NPV | Currency value at a chosen required return | Depends on forecast and discount rate |
| IRR | Periodic break-even discount rate | Sign changes may make roots ambiguous |
| Simple payback | Undiscounted recovery time | Ignores timing value and later flows |
| Discounted payback | Recovery from present-value receipts | Still ignores flows after recovery |
NPV = −initial cost + sum of CFt divided by (1 + r)^t. CFt belongs to period t and r belongs to that same interval. Annual flows require an annual rate; monthly flows require a matching monthly rate. Keep empty periods as zeros instead of moving later receipts forward.
Worked scenario: a two-year equipment upgrade
A packaging business pays $100,000 now and expects $60,000 at each of the next two year ends. There are no sale proceeds afterward. Management selects a 10% annual required return. The cash-flow vector is negative 100000, 60000, 60000; in the calculators, enter initial investment 100000 and future flows 60000, 60000.
| Period | Cash flow | Present value at 10% |
|---|---|---|
| 0 | −$100,000 | −$100,000.00 |
| 1 | $60,000 | $54,545.45 |
| 2 | $60,000 | $49,586.78 |
| Net | $20,000 nominal | $4,132.23 |
NPV is −100,000 + 60,000 / 1.10 + 60,000 / 1.10² = $4,132.23 after rounding. The positive result means the forecast exceeds the selected hurdle, not that the receipts are certain or the business can afford the outlay.
For IRR, set that expression to zero with the rate unknown. Let x equal one plus the rate. Multiplying through gives 100,000x² − 60,000x − 60,000 = 0. The positive x root is approximately 1.1306623863, so annual IRR is 13.0662%, displayed as 13.07%. It exceeds the 10% hurdle under these inputs.
After year one, $40,000 remains unrecovered in nominal terms. If second-year receipts accrue evenly, simple payback is one plus $40,000 divided by $60,000, or 1.6667 years. The calculator displays 1.67 periods. On a strict year-end payment model, actual cash recovery occurs at the second year end instead.
Discounted payback uses the same fractional convention applied to discounted annual amounts: one plus $45,454.54545 divided by $49,586.77686 = 1.9167 years, displayed as 1.92 periods. This is a planning interpolation, not a change to the year-end assumptions used by NPV and IRR. Label it so reviewers do not infer a payment midway through the year.
Worked scenario: a smaller three-year machine
An alternative costs $60,000 and produces $25,000 at each of three year ends, with no terminal proceeds. The required return remains 10%. Enter initial cost 60000 and receipts 25000, 25000, 25000.
| Period | Receipt | Present value | Cumulative net present value |
|---|---|---|---|
| 0 | −$60,000 | −$60,000.00 | −$60,000.00 |
| 1 | $25,000 | $22,727.27 | −$37,272.73 |
| 2 | $25,000 | $20,661.16 | −$16,611.57 |
| 3 | $25,000 | $18,782.87 | $2,171.30 |
NPV is $2,171.30. The periodic zero-NPV solution is approximately 12.0444%, displayed as 12.04%. After two years, nominal receipts total $50,000, leaving $10,000. Fractional simple payback is 2 + $10,000 / $25,000 = 2.40 periods. Discounted payback is approximately 2.8844 years, displayed as 2.88 periods. Strictly timed year-end recovery occurs at year three for both measures.
For comparable, mutually exclusive and feasible alternatives at this hurdle, the first scenario has greater NPV: $4,132.23 against $2,171.30. The difference calculated before rounding is $1,960.93. It also has a higher IRR and shorter payback here, so no ranking conflict arises.
Its outlay is nevertheless $40,000 larger. If only $60,000 of capital is available and financing is unavailable, it is infeasible despite higher NPV. Different service lives also deserve attention: when the equipment must keep operating beyond these horizons, include replacement or continued service over a comparable decision horizon before treating this as a final procurement choice.
When the metrics disagree, inspect scale and timing
A high percentage on a small project is not automatically more valuable than a lower percentage on a larger one. When NPV and IRR rank otherwise comparable alternatives differently, examine scale, timing and the required return. NPV at an appropriate discount rate directly measures the modeled currency-value objective.
IRR becomes awkward when flows change sign more than once. An initial outlay, positive operating receipts and a final cleanup liability can create multiple mathematical roots. The calculator deliberately rejects later negative receipts rather than selecting a convenient root silently. Use signed NPV analysis and, where helpful, inspect a rate profile.
Simple payback is a liquidity screen. A company can reasonably require recovery within a policy window, but that cutoff is a decision rule, not a complete valuation theorem. Receipts after payback are ignored, so a fast-paying investment can still be unattractive once later obligations are included.
Discounted payback repairs the treatment of waiting but not that truncated horizon. It can remain unrecovered even when nominal cash covers the outlay. Neither payback measure establishes a percentage return or replaces a complete signed cash-flow forecast.
Checks before presenting the recommendation
- Reconcile time zero. Include the initial investment once. Some spreadsheet functions expect it outside their list of discounted future flows.
- Match price and rate bases. Nominal forecasts need nominal rates; real forecasts need real rates.
- Test major drivers. Change volumes, margins, useful life and required return before combining downside assumptions.
- Keep internal precision. Round displayed money and percentages only after completing the arithmetic.
- State omissions. Identify whether taxes, salvage, working capital and replacements are present.
Present the complete timeline beside the three outputs. A reviewer can then reproduce the numbers and challenge the commercial assumptions without reconstructing an unexplained headline percentage. These are educational models, not financial advice; the quality of the decision still rests on the forecast and the circumstances in which the investment must operate.
Calculators used in this guide
Frequently asked questions
Does positive NPV guarantee success?
No. It describes the forecast at the chosen rate. Actual amounts, timing and liquidity restrictions can differ.
Why are fractional and year-end paybacks different?
Fractional payback interpolates receipts within the recovery period. If payment truly arrives only at period end, cash recovery occurs at that boundary.
Can IRR be compared directly with a loan rate?
Only after checking periods, compounding, fees, risk and cash-flow definitions. Project IRR is not automatically an owner return after financing.
What if no payback occurs?
Report no recovery within the supplied horizon. Additional receipts need a defensible forecast rather than automatic extrapolation.
Are these annual rates?
The examples use annual intervals. The same calculation applied to monthly receipts produces a monthly rate, not an automatically annualized one.
Sources and standards
About the author
Dr. Hassan Khames Eliwa holds a PhD in Construction & Built Environment and has more than 20 years of international project controls experience. He is Director of Eliwa Project Controls Limited in Auckland and founder of PMMilestone.org and PMMilestone.com.
Buy me a coffee